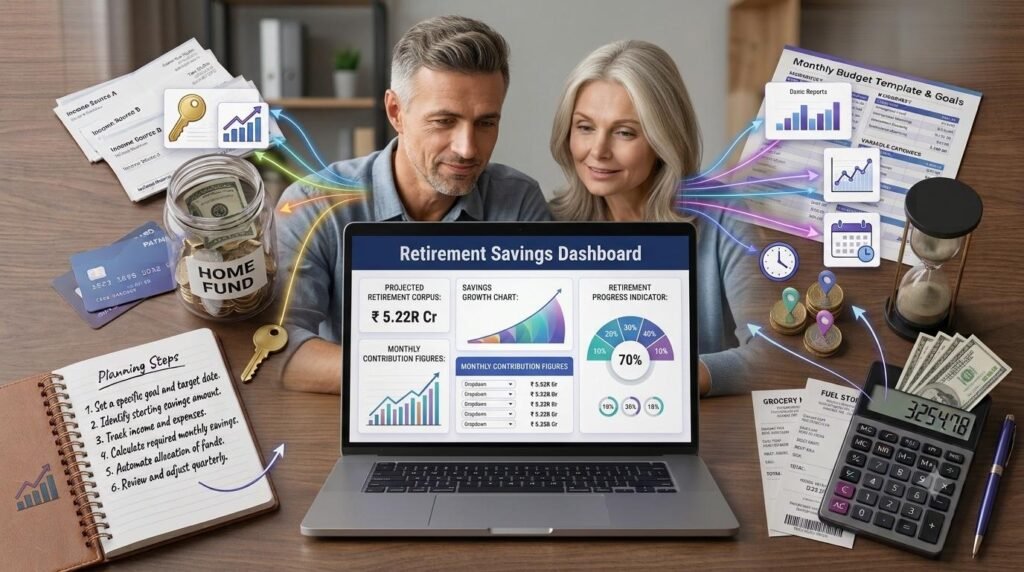
Learning how to plan for retirement is one of the most important steps toward building long-term financial security. Whether you are in your twenties, thirties, forties, or approaching retirement, preparing early can give you more time to build savings and organize your future financial needs.
Retirement planning is not simply about accumulating a large amount of money. It involves estimating your future expenses, setting a realistic savings target, understanding inflation, and deciding how much you should contribute regularly.
Learning how to plan for retirement early can help you set realistic financial goals and build a stronger savings strategy.
With a clear strategy and consistent financial habits, you can work toward a retirement plan that supports your expected lifestyle and long-term goals.
Table of Contents
ToggleWhat Is Retirement Planning?
Retirement planning is the process of preparing financially for the years when you may no longer receive regular employment income.
It involves estimating how much money you may need after retirement, identifying your existing financial resources, and creating a savings or investment strategy to meet your future requirements.
A retirement plan generally considers:
Your current age and expected retirement age
Your expected retirement lifestyle
Current savings and investments
Monthly retirement expenses
Expected inflation
Potential investment returns
Your expected retirement duration
Other possible sources of retirement income
The purpose is to create a practical financial roadmap rather than depend on guesswork.
Why Is It Important to Plan for Retirement Early?
Starting retirement planning early can provide several advantages.
1. More Time to Build Savings
When you begin saving early, your money has more time to potentially grow through investment returns and compounding.
Even relatively small monthly contributions can become meaningful over a long savings period.
2. Greater Financial Flexibility
Starting early gives you more opportunities to adjust your savings amount, investment approach, and retirement timeline as your financial circumstances change.
3. Better Preparation for Inflation
The cost of everyday expenses may increase over time. Planning early helps you consider how much your future lifestyle could cost.
4. Reduced Financial Pressure
Building savings gradually can reduce the pressure of trying to accumulate a large retirement fund in the final years before retirement.
5. More Control Over Retirement Goals
A clear plan helps you decide when you want to retire, how much you may need, and what steps you should take to work toward that target.
Understanding how to plan for retirement gives you more time to prepare for future expenses and long-term financial responsibilities.
How to Plan for Retirement: 10 Practical Steps
Creating a retirement strategy becomes easier when you break it into manageable steps.
1. Determine Your Retirement Age
Start by deciding approximately when you would like to retire.
Your retirement age affects how many years you have available to save and how long your retirement fund may need to support your expenses.
For example, retiring at 55 instead of 60 means you may have fewer earning years and a longer retirement period to finance.
Choose an age that reflects your career plans, financial situation, and personal preferences.
2. Estimate Your Future Monthly Expenses
Think about the expenses you may have after retirement.
These may include:
Housing and utility bills
Food and household expenses
Healthcare and medical costs
Transportation
Insurance premiums
Travel and entertainment
Family responsibilities
Personal and lifestyle expenses
Your retirement lifestyle will influence how much money you need to save.
A realistic expense estimate is more useful than selecting an arbitrary retirement target.
3. Account for Inflation
Inflation is an important factor in long-term retirement planning.
For example, if your current monthly expenses are ₹30,000 and you assume annual inflation of 6%, those expenses could become approximately ₹1.72 lakh per month after 30 years.
This is an illustration based on a constant inflation assumption, not a prediction.
Ignoring inflation can cause you to underestimate the amount required to maintain your lifestyle in the future.
An important part of how to plan for retirement is preparing for the rising cost of everyday goods and services.
4. Calculate Your Retirement Savings Target
Once you estimate your future monthly expenses, you can work toward determining the retirement corpus you may need.
A retirement corpus is the total amount of money accumulated to support your financial needs after leaving work.
Your target will depend on your retirement duration, expected expenses, potential investment returns, inflation, and other income sources.
Use our Retirement Savings Calculator to estimate your future retirement corpus and compare it with your projected savings.
5. Review Your Existing Savings
Before deciding how much more you need to save, review your existing retirement investments and savings.
Consider the funds you have already allocated for retirement, including eligible long-term savings and investment accounts.
Enter your current retirement savings into the calculator to understand how they may contribute to your future corpus under your chosen return assumptions.
6. Set a Realistic Monthly Savings Contribution
A consistent monthly contribution can help you work toward your retirement goal.
Start with an amount that fits your current income and essential expenses. As your income increases, consider increasing your retirement savings contribution.
The important thing is to create a sustainable habit instead of choosing an amount that puts unnecessary pressure on your monthly budget.
Knowing how to plan for retirement also means choosing a monthly savings contribution that you can maintain consistently.
7. Understand the Role of Investment Returns
Your retirement savings may grow through investment returns over time, but returns are not guaranteed.
Different investment choices carry different levels of risk, and actual performance can vary from year to year.
When planning for retirement, avoid assuming that a high annual return will continue indefinitely.
Use reasonable assumptions and review your financial plan as market conditions and personal circumstances change.
8. Prepare for a Longer Retirement Period
Your retirement savings may need to support you for many years after you stop working.
Consider your expected retirement age and the age up to which you want your financial plan to provide for your expenses.
Planning for a longer retirement duration can help you understand the importance of building an adequate fund.
9. Create an Emergency Savings Buffer
Retirement savings and emergency savings serve different purposes.
An emergency fund can help you manage unexpected expenses without immediately withdrawing money from long-term investments.
You can use our Emergency Fund Calculator to estimate an appropriate emergency savings target.
10. Review and Update Your Retirement Plan
Your financial situation will not remain the same throughout your life.
Your income, monthly expenses, family responsibilities, savings, and retirement goals may change.
Review your plan periodically and update your calculations when important financial changes occur.
A retirement plan should be flexible enough to adapt to your circumstances.
If you are wondering how to plan for retirement, start by reviewing your current savings, estimating future expenses, and choosing a suitable retirement age.
How Much Money Do You Need for Retirement?
There is no universal retirement savings target because everyone’s financial requirements are different.
A person planning a simple lifestyle may need a different retirement corpus from someone expecting higher healthcare, travel, housing, or family expenses.
Your estimated retirement requirement depends on several factors:
Expected monthly expenses at retirement
Number of years in retirement
Inflation rate
Expected investment returns after retirement
Existing savings and other retirement income
For a more useful estimate, consider all these factors together rather than relying on a fixed retirement savings rule.
Common Retirement Planning Mistakes to Avoid
Even a good savings plan can become less effective when important factors are overlooked.
Ignoring Inflation
Using today’s expenses without accounting for future price increases can result in an unrealistic retirement target.
Starting Too Late
Delaying savings reduces the time available for your investments to potentially grow.
Assuming Guaranteed Returns
Investment returns can fluctuate. Planning around unrealistic return expectations may create an inaccurate picture of your future finances.
Forgetting Healthcare Expenses
Healthcare costs can be an important part of retirement spending. Include an appropriate allowance in your financial planning.
Not Reviewing Your Savings Plan
A plan created many years ago may no longer reflect your current financial circumstances.
Using Retirement Savings for Unplanned Spending
Without a separate emergency fund, unexpected expenses may force you to withdraw money intended for long-term retirement needs.
A clear understanding of how to plan for retirement can help you avoid common mistakes and make more informed financial decisions.
Tools That Can Help You Organize Your Financial Plan
Along with retirement planning, other financial tools can help you manage different parts of your money.
Budget Planner
Organize your income and expenses and create a monthly budget.
Savings Goal Calculator
Calculate the monthly savings required to reach a specific financial goal.
Compound Interest Calculator
Explore how savings may grow through compound interest.
Expense Tracker
Track spending and find ways to save more.
Frequently Asked Questions
It is generally useful to start as early as possible. Beginning early provides more time to save and potentially benefit from compounding. However, it is never too late to review your finances and create a retirement strategy.
The amount depends on your current age, retirement age, existing savings, expected expenses, inflation, and investment returns. A retirement calculator can help you estimate a suitable contribution under your chosen assumptions.
A retirement corpus is the total fund accumulated to support your expenses and financial needs after retirement.
Inflation increases the cost of goods and services over time. As a result, the same amount of money may purchase fewer goods and services in the future.
Yes. You can still create a retirement plan by reviewing your available savings period, adjusting your contribution amount, evaluating expenses, and setting realistic goals.
Yes. Healthcare and medical expenses can be significant during retirement. Consider them when estimating your future financial needs.
A retirement savings calculator provides estimates based on the information and assumptions entered. Actual investment returns, inflation, taxes, fees, and expenses may differ, so results should not be treated as guaranteed outcomes.
Final Thoughts
Understanding how to plan for retirement can help you make more informed decisions about your long-term financial future.
The best way to learn how to plan for retirement is to review your financial goals regularly and adjust your savings strategy as your circumstances change.
Start by estimating your expenses, reviewing your existing savings, considering inflation, and setting a realistic monthly contribution. Then review your progress regularly and make adjustments when your circumstances change.
You do not need to build your entire retirement fund overnight. Consistent saving, realistic expectations, and regular financial reviews can help you work toward greater financial preparedness.
Use our Retirement Savings Calculator to estimate your retirement corpus, review your projected savings, and explore how different monthly contributions may affect your retirement plan.
Disclaimer: This article is for educational and informational purposes only and does not constitute financial, investment, tax, or legal advice. Investment returns and inflation are uncertain. Consider consulting a qualified financial professional before making decisions about your retirement savings.
Retirement Savings Calculator
Estimate your retirement corpus, account for inflation, and calculate the monthly savings needed to work toward your retirement goals.
Emergency Fund Calculator
Estimate your emergency savings target and prepare for unexpected expenses with a practical savings plan.
Explore More Free Tools & Utilities
Discover a collection of free calculators, productivity tools, and useful online utilities designed to make your everyday tasks easier.
Explore More Digital Tools at DigiMarket
Looking for more useful digital resources and productivity solutions? Explore DigiMarket – The Marketplace for Digital Treasures to discover digital products, practical resources, and tools designed to support your online work and learning.
Whether you are exploring digital resources for business, marketing, or productivity, DigiMarket offers a growing collection of useful digital solutions.
Learn More with Prernaa
Want to improve your digital skills and learn practical ways to work smarter? Explore Prernaa – Inspiring Learning for useful learning resources, practical guides, and educational content.
Discover helpful information that can support your personal learning and digital growth.